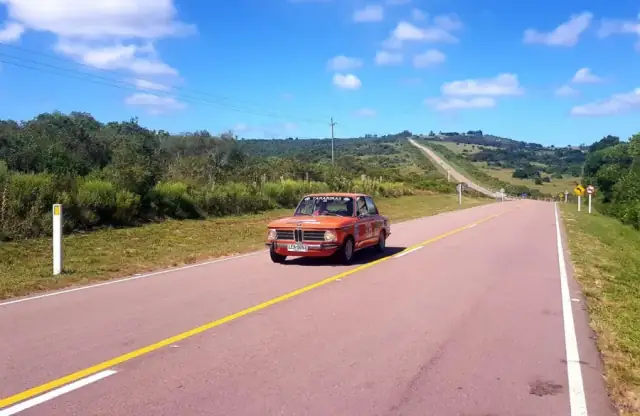
Importing used vehicles has historically been prohibited in Uruguay, except for specific exceptions provided for in current legislation. One of the most notable concerns classic vehicles.
Law No. 19,996, enacted on 3 November 2021, introduced a significant exception by allowing the permanent import of classic vehicles fifty (50) years old or older, exempt from all customs duties (see article).
Current legal framework
Article 330 of Law No. 19,996 allows vehicles manufactured before 1971 to be imported tax-free, provided they are not subsequently sold in Uruguay. The current rule states:
“The permanent import into the national customs territory of classic vehicles fifty years old or older is authorised, exempt from all customs or other duties payable on import, including the minimum surcharge.
Under no circumstances may they be sold within the national territory.
Failure to comply with these conditions shall constitute the customs offence set out in article 208 of Law No. 19,276 of 19 September 2014 (Customs Code of the Oriental Republic of Uruguay).
The Executive Branch shall issue regulations for this provision within one hundred and eighty days.”
Changes proposed in the 2025–2029 Budget Bill
The 2025–2029 National Budget Bill introduces substantial changes to the current regime. The main proposed provisions are:
- Substitute taxation: a single rate of 23% on the invoice or declared value of the goods, replacing the exemption from all customs and domestic taxes that normally apply to permanent imports.
- Eligible importers: only individuals may import; legal entities are excluded.
- Limit on transactions: each individual may make up to two imports per year, under the terms and conditions set by the regulations.
- Restrictions by type of vehicle: vehicles that are not classic motor cars, such as motorcycles and motorhomes, are expressly excluded.
- Prohibition on sale: vehicles imported under this regime may not be sold in Uruguay for five (5) years from their entry.
Unless expressly stated otherwise, the measures in the bill would come into force on 1 January 2026. Parliamentary debate is expected to continue over the coming months, with the Law likely to be enacted towards the end of the year. Since changes may be made to the original bill during the legislative debate, a detailed analysis will be essential once the Law has been passed.
Conclusions
If the 2025–2029 National Budget Bill is approved, the current full exemption could be replaced by a controlled tax system, with a flat rate of 23% on the value of the vehicle instead of the exemption. Stricter requirements are also introduced regarding who may import and the use of the vehicles.
For personalised advice, please contact the INGLOBAL team at info@inglobal.com.
Our team is available to advise you.